
 By Islam Baraka
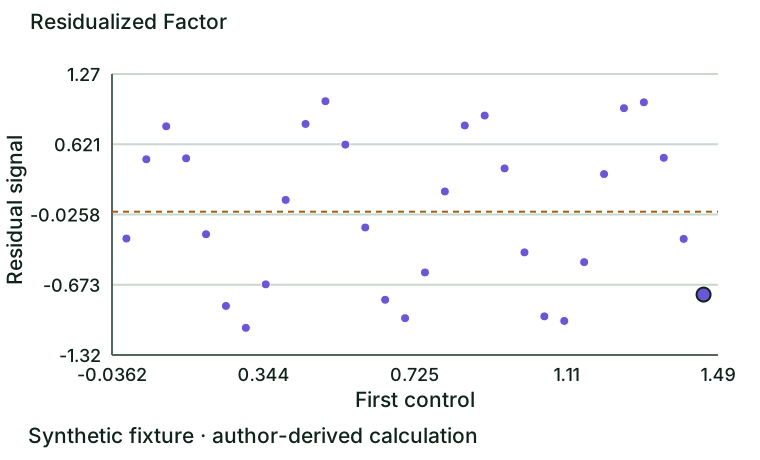
Extract the part of a cross-sectional signal that is linearly unexplained by specified control characteristics. The useful result is not just a scalar. You should be able to trace it back to eligible observations, explain which convention produced it and recognize when the calculation should stop.
This tutorial builds Equal-weight cross-sectional residualization with intercept and full-rank controls. The residual is not divided by residual volatility. You will calculate a small example, run matching Python and TypeScript implementations, inspect a controlled synthetic case and change one assumption in a guided lab. No historical market performance is claimed.
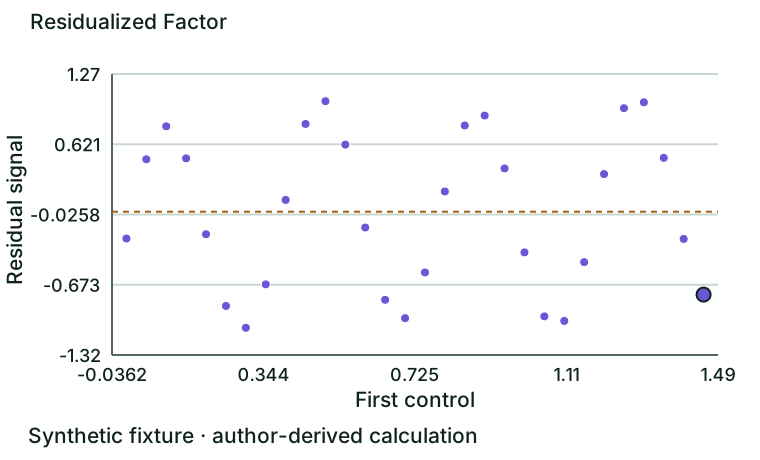
The chart shows the canonical fixture. Read the axis units before comparing values: a return, a score, a weight and a statistical diagnostic are different objects. Its numerical source is the same fixture used by the executable examples. Open the full-size chart when you need to inspect small labels.
Start with the question, then the mechanism
The residual is defined relative to a chosen explanatory span. It is not a permanently purified version of the characteristic. A new control, a new population or a nonlinear transformation changes that span and can change the result. The lab adds a known multiple of a control to the signal; the fitted part changes but the residual remains the same. That is a more useful demonstration than merely showing a smaller correlation coefficient.
Transform the fixed formation cross section without using future holding returns.
Specify the transformation before specifying the portfolio
A useful factor transformation has an invariant you can inspect. A quantile sort has deterministic membership and bucket weights that sum to one. A composite exposes each weighted contribution. Sector demeaning has zero residual sum within each group. Projection removes the span of declared controls. Winsorized ranks expose the clipping thresholds and tied ordering. Testing that invariant is more informative than checking whether a single example returns an attractive number.
The cross section is frozen at formation. IDs are stable identifiers rather than changing display tickers; ties use a stated rule. A research pipeline must record exclusions before looking at holding-period outcomes, retain delisted names when appropriate and preserve historical sector or risk estimates. The implementation accepts fully aligned arrays, checks their lengths and identity uniqueness, and never joins observations by their current row position across different dates.
Signal neutrality and portfolio neutrality are different. Demeaning a score does not guarantee that a later nonlinear sort has neutral sector weights. A residual can be orthogonal to a control before clipping and lose that property after clipping. Converting scores to weights introduces constraints, gross exposure, borrowing and transaction costs. Apply and verify constraints at the final weight stage if the production objective is a neutral portfolio.
For projection methods, controls must be linearly independent after the intercept is included. Duplicating a column is not additional information. The reference solver rejects a singular design rather than selecting a column without telling the caller. For ranking methods, numerical ties and economic equivalence must not be confused: the stable-ID tie break is reproducible, but it has no investment meaning. Compare transformations on the same cross section and document which property you are trying to preserve.
Freeze the definition
x is the signal vector, C includes an intercept and the supplied controls, gamma is the OLS coefficient vector, and u is the residual signal.
The sources establish the method's research context; the stated variant fixes the implementation choices for this package. See MSCI, Foundations of Factor Investing. Where a teaching convention differs from a published portfolio or test, it is labeled explicitly rather than borrowing the published method's empirical conclusions.
Work a small example before running the code
For control (-1,0,1) and signal (0,1,0), the intercept is 1/3 and the slope is zero. Residuals (-1/3,2/3,-1/3) sum to zero and have zero inner product with the control. Adding 2×control to the original signal leaves these residuals unchanged.
The machine-readable hand check is saved separately from the larger chart fixture. It asserts scores against [-0.333333333, 0.666666667, -0.333333333]. Some hand checks use a different small input from the prose example to test the same invariant from another direction. For a model with several regressors, a one-row attribution example cannot estimate the loadings; the multi-period executable fixture supplies the necessary observations.
To audit the arithmetic, carry full precision through intermediate values and round only for display. Ask whether the result's unit is consistent with the formula. Then consider a limiting case: does the method return an explicit rejection or undefined result when its denominator or identifying variation disappears?
Prepare data without borrowing from the future
| Input | Type | Meaning |
|---|---|---|
| ids | string[] | Unique entities. |
| scores | number[] | Finite signal values. |
| controls | number[][] | N by K finite controls; intercept is inserted by the implementation. |
All calls also require formation_at, inputs_available_at and as_of as real ISO calendar dates. Inputs must be available by formation; formation cannot exceed the evaluation cutoff. Evaluation topics additionally require outcome start, end and availability dates. These envelope checks reject impossible chronology but cannot certify the provenance of individual rows. Your adapter must verify IDs, timestamps, frequency, currency, total-return adjustments, release dates and source vintages before building the arrays.
Missing, nonfinite, boolean or string-valued numbers are not silently repaired. The complete-case contract is intentional: changing eligibility changes the quantity being measured. Preserve the rejected records and the reason in a data-quality report, then choose a documented repair or a different model. Do not turn an undefined quantity into zero to make a chart look complete.
Follow the execution path
- Freeze the cross section. Transform the fixed formation cross section without using future holding returns.
- Apply the declared transformation. Retain the inputs and the intermediate quantities; alignment is part of correctness.
- Inspect intermediate values. Calculate at full precision using the declared variant, not a convenient substitute.
- Check the defining invariant. Check the method’s invariant and preserve undefined outcomes separately from numeric zero.
- Compare the alternative. A transformed signal is not a feasible portfolio until weights, costs, capacity and constraints are specified.
Run the reference implementation
From the downloaded topic directory:
python examples/run.py
python -m unittest discover -s tests -p "test_*.py"
npx tsc -p implementations/typescript/tsconfig.json
node tests/test-typescript.mjs
The Python calculation has no third-party runtime dependency. TypeScript needs a compiler and an ES2022-capable JavaScript runtime. The public call accepts one JSON-shaped input and returns a discriminated success or error object. A minimal Python integration is:
from pathlib import Path
import importlib.util, json

root = Path.cwd()  # Run from this topic directory.
spec = importlib.util.spec_from_file_location("topic", root / "implementations/python/algorithm.py")
module = importlib.util.module_from_spec(spec)
spec.loader.exec_module(module)
data = json.loads((root / "datasets/canonical-input.json").read_text())
result = module.compute(data)
if result["status"] != "ok":
    raise ValueError(result["code"])
print(result["primary"])
After compilation, the equivalent TypeScript module can be used from JavaScript:
import { readFileSync } from 'node:fs';
import { compute } from './implementations/typescript/dist/algorithm.js';
const input = JSON.parse(readFileSync('./datasets/canonical-input.json', 'utf8'));
const result = compute(input);
if (result.status !== 'ok') throw new Error(result.code);
console.log(result.primary);
The canonical primary display is 2.88657986e-15. More informative output fields include:
| Field | Canonical value / first values |
|---|---|
| ids | ["SYN-001", "SYN-002", "SYN-003", "SYN-004", "SYN-005", "SYN-006", …] |
| scores | [-0.247297753, 0.482734996, 0.786520597, 0.491577015, -0.20751181, -0.868159214, …] |
| residuals | [-0.247297753, 0.482734996, 0.786520597, 0.491577015, -0.20751181, -0.868159214, …] |
| fitted | [0.247297753, 0.284621095, 0.313053006, 0.333886165, 0.349137667, 0.361356718, …] |
| coefficients | [0.149362283, 0.839831537, 0.0979354699] |
Inspect the complete returned object rather than reducing every use case to primary. That field is a playground convenience; the named intermediate and result fields preserve the method's meaning. Both languages use the same defaults and reason codes and do not mutate the input. Package tests compare the whole output tree, while independent mathematical checks avoid treating one implementation as the sole authority for the other.
Use the playground as an experiment
Open the topic's Playground tab or the self-contained guided lab. It starts from a meaningful canonical preview. Choose a scenario, predict the result, use Step to follow the calculation, and explain the evidence before pressing Play. Back and Reset let you revisit exactly the same state. Reduced-motion mode advances one deliberate step instead of running a timed sequence.
The main control is Added first-control exposure, ranging from -3 to 3 with default 0. The comparison scenario is Duplicated control column. Joint residualization is invariant to added control-span signal and rejects collinearity. Every change recomputes the result through the validated TypeScript kernel; it does not select a prerecorded result.
The deliberate failure scenario, Collinear control columns, should return SINGULAR_DESIGN. First explain which assumption failed. Then return to the canonical case and identify the information that makes the calculation possible. This rejection is part of the lesson: it prevents an invalid model from producing a plausible-looking number.
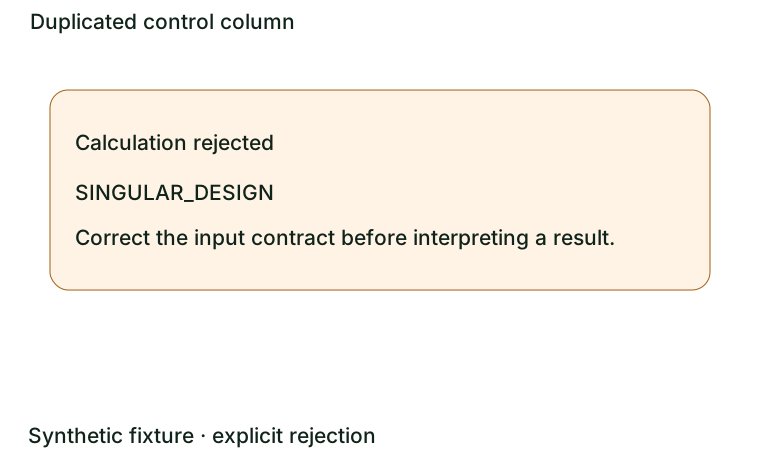
This second chart uses the comparison scenario at the default parameter. The caption and diagnostics in the lab explain what changes and what remains invariant. Identical output can be the correct outcome of an invariance experiment; do not mistake it for a broken control.
Avoid these interpretation failures
- Do not invert a singular design silently.
- Residualization does not prove causal independence or remove nonlinear dependence.
- The eligible universe defines the projection; changing it changes the answer.
A transformed signal is not a feasible portfolio until weights, costs, capacity and constraints are specified.
Check your understanding
Predict: Can winsorizing an orthogonal residual preserve orthogonality automatically?
Explain: No. Nonlinear clipping can create new correlation with controls. Check the final transformed output or solve the final constraints.
Investigate: Run the canonical case, the comparison and the deliberate rejection. Save the input, output and one sentence explaining each difference. Identify a field whose unit could be confused with another field, and describe the consequence of that confusion.
Transfer: Before substituting real data, write the upstream eligibility and alignment rules. Name the source vintage, decision time and missing-value policy. Then identify one out-of-sample or data-quality check needed for your intended use. A successful synthetic calculation is a correctness demonstration, not evidence that the market rewards the signal.
What this package does and does not establish
The implementation makes the declared formula reproducible, exposes intermediates and rejects known invalid inputs. The sources motivate the method. The synthetic fixture lets you control one mechanism at a time. A named historical case remains deferred until its source observations and decision-time provenance can be archived; no invented returns are presented as real history.
Production use needs dataset-specific validation, monitored numerical limits, error logging, independent review and an execution or inference design appropriate to the application. See the source-package data contract and reference ledger for the full boundary. Educational material is not a recommendation to buy, sell or allocate capital.
Sources and further reading
- MSCI, Foundations of Factor Investing. Construction choices matter; this package does not reproduce an MSCI index or its current methodology.
Choosing the method and continuing the lesson
This lesson is for analysts and developers who can work with aligned numerical arrays, means and return units. Regression and statistical-test topics also assume familiarity with residuals and sampling uncertainty; review the linked prerequisite before interpreting an inferential result.
| Decision | Declared approach | Neighbor or alternative |
|---|---|---|
| Residualization versus ranking | Removes linear control exposure in metric space. | A later rank transformation can reintroduce exposure. |
| Joint versus sequential projection | Jointly partials out all controls. | Sequential demeaning is generally order-dependent when controls correlate. |
Use the declared approach when its input and interpretation match your research question. If you choose the alternative, freeze a new convention and rerun the examples; changing a label is not enough to change the calculation.
Related concepts
Factor score weighting, Point-in-time dataset. For any use with observed market data, keep the point-in-time dataset boundary explicit.
Learning connections
- Prerequisite: Beta-Neutral Factor. Establish the inputs or mathematical distinction used here.
- Comparison: Beta-Neutral Factor. Compare its question and output units before substituting it for this method.
- Continue with: Winsorized Rank Factor. Carry the same formation clock and declared units into the next calculation.
Rendered from the canonical Mermaid sources linked by this article.
Calculation flow
ReferencesPrimary sources and evidence notesExpand the source trail, evidence role, and limitations behind the engineering choices.
Expand the source trail, evidence role, and limitations behind the engineering choices.
MSCI, Foundations of Factor Investing
- Source: MSCI, Foundations of Factor Investing
- Version / date: 2013
- Accessed: 2026-09-22
- Supports: Construction choices matter; this package does not reproduce an MSCI index or its current methodology.
- Limitations: methodological context only; no claim that the source validates this synthetic sample or every educational convention.
- Reuse: cited, not copied. No source dataset is redistributed.
Evidence boundaries
The formulas are operationalized in the canonical README with explicit package conventions. Original synthetic fixtures isolate mechanisms and are not a historical performance claim. External source access can be restricted; the MacKinlay archive is a bibliographic reference, not a claim that its full text was retrieved during this build.
Historical case decision: deferred. A named empirical case would require a separately archived point-in-time universe, source vintage and outcome design. A synthetic control is used here to demonstrate partial signal scatter without attributing invented observations to a market. This limits empirical coverage; it does not change the mathematical contract.
When using live data, archive the retrieval date, provider query, license, currency, frequency, adjustment basis and transformation log. Do not imply that the primary authors endorsed this educational implementation.
Full dependency-light reference implementations in both supported languages.
/** D17 reference algorithms. JSON boundary validation is deliberate and shared.
 * Arrays are copied before sorting; callers' inputs are never mutated.
 * QR solves least squares without forming normal equations.
 */
type Data = Record<string, any>;
type Result = Record<string, any>;
class ContractError extends Error {
}
const fail = (code: string): never => { throw new ContractError(code); };
const num = (x: unknown): number => typeof x === 'number' && Number.isFinite(x) ? x : fail('INVALID_NUMBER');
function integer(x: unknown, lo: number, hi: number): number { const v = num(x); return Number.isInteger(v) && v >= lo && v <= hi ? v : fail('INVALID_PARAMETER'); }
function vec(x: unknown, min = 1): number[] { if (!Array.isArray(x))
    fail('INVALID_SHAPE'); const a = x as unknown[]; if (a.length < min)
    fail('INSUFFICIENT_DATA'); return a.map(num); }
function mat(x: unknown, min = 1): number[][] { if (!Array.isArray(x) || x.length < min)
    fail('INSUFFICIENT_DATA'); const a = (x as unknown[]).map(v => vec(v)); if (new Set(a.map(r => r.length)).size !== 1)
    fail('LENGTH_MISMATCH'); return a; }
function same(...x: {
    length: number;
}[]): void { if (new Set(x.map(a => a.length)).size !== 1)
    fail('LENGTH_MISMATCH'); }
function ids(d: Data, n: number): string[] { required(d, ['ids']); if (!Array.isArray(d.ids) || d.ids.length !== n)
    fail('LENGTH_MISMATCH'); if (d.ids.some((v: unknown) => typeof v !== 'string' || !/^[A-Za-z0-9_.-]+$/.test(v)))
    fail('INVALID_ID'); if (new Set(d.ids).size !== n)
    fail('DUPLICATE_ID'); return [...d.ids]; }
function required(d: Data, keys: string[]): void { for (const key of keys)
    if (!Object.hasOwn(d, key))
        fail('MISSING_FIELD'); }
function validDate(v: unknown): boolean { if (typeof v !== 'string' || !/^\d{4}-\d{2}-\d{2}$/.test(v) || v.startsWith('0000'))
    return false; const date = new Date(v + 'T00:00:00Z'); return Number.isFinite(date.valueOf()) && date.toISOString().slice(0, 10) === v; }
function context(d: Data, op: string): void {
    const keys = ['as_of', 'formation_at', 'inputs_available_at'];
    const evaluation = ['ic', 'rank_ic', 'spread', 'decay'].includes(op);
    if (evaluation)
        keys.push('outcomes_start_at', 'outcomes_end_at', 'outcomes_available_at');
    required(d, keys);
    if (keys.some(k => !validDate(d[k])))
        fail('INVALID_DATE');
    if (d.formation_at > d.as_of || d.inputs_available_at > d.formation_at)
        fail('FUTURE_INPUT');
    if (evaluation) {
        if (d.outcomes_start_at < d.formation_at || d.outcomes_end_at < d.outcomes_start_at)
            fail('INVALID_OUTCOME_WINDOW');
        if (d.outcomes_available_at < d.outcomes_end_at)
            fail('INVALID_DATE_ORDER');
        if (d.outcomes_available_at > d.as_of)
            fail('IMMATURE_OUTCOME');
    }
}
const sum = (a: number[]): number => a.reduce((s, v) => s + v, 0);
const mean = (a: number[]): number => sum(a) / a.length;
const dot = (a: number[], b: number[]): number => sum(a.map((v, i) => v * b[i]));
const tr = (a: number[][]): number[][] => a[0].map((_, j) => a.map(r => r[j]));
const mm = (a: number[][], b: number[][]): number[][] => { const cols = tr(b); return a.map(row => cols.map(col => dot(row, col))); };
function sd(x: number[], ddof = 0): number { const m = mean(x); return Math.sqrt(sum(x.map(v => (v - m) ** 2)) / (x.length - ddof)); }
function standard(x: number[]): number[] { const m = mean(x), s = sd(x); if (s <= 1e-14 * Math.max(1, ...x.map(Math.abs)))
    fail('CONSTANT_CROSS_SECTION'); return x.map(v => (v - m) / s); }
function corr(x: number[], y: number[]): number | null { same(x, y); if (Math.max(...x) === Math.min(...x) || Math.max(...y) === Math.min(...y))
    return null; const xm = mean(x), ym = mean(y), a = x.map(v => v - xm), b = y.map(v => v - ym), den = Math.sqrt(dot(a, a) * dot(b, b)); return den <= 0 ? null : Math.max(-1, Math.min(1, dot(a, b) / den)); }
function ranks(x: number[]): number[] { const order = x.map((_, i) => i).sort((a, b) => x[a] - x[b]); const out = x.map(() => 0); let start = 0; while (start < x.length) {
    let end = start + 1;
    while (end < x.length && x[order[end]] === x[order[start]])
        end++;
    for (let j = start; j < end; j++)
        out[order[j]] = (start + 1 + end) / 2;
    start = end;
} return out; }
function quantile(x: number[], p: number): number { const y = [...x].sort((a, b) => a - b), h = (y.length - 1) * p, j = Math.floor(h), f = h - j; return y[j] * (1 - f) + y[Math.min(j + 1, y.length - 1)] * f; }
function compound(x: number[]): number { if (x.some(v => v <= -1))
    fail('INVALID_RETURN'); return Math.expm1(sum(x.map(Math.log1p))); }
/** erfc(|z|/sqrt(2)) via regularized Gamma(1/2,x); converged series/CF. */
function normalP(z: number): number {
    const x = z * z / 2, a = 0.5, lg = 0.5723649429247001;
    if (x === 0)
        return 1;
    const factor = Math.exp(-x + a * Math.log(x) - lg);
    if (x < a + 1) {
        let term = 1 / a, total = term, ap = a;
        for (let i = 1; i < 500; i++) {
            ap++;
            term *= x / ap;
            total += term;
            if (Math.abs(term) < Math.abs(total) * 1e-15)
                break;
        }
        return Math.max(0, 1 - total * factor);
    }
    let b = x + 1 - a, c = 1e300, d = 1 / b, h = d;
    for (let i = 1; i < 500; i++) {
        const an = -i * (i - a);
        b += 2;
        d = an * d + b;
        if (Math.abs(d) < 1e-300)
            d = 1e-300;
        c = b + an / c;
        if (Math.abs(c) < 1e-300)
            c = 1e-300;
        d = 1 / d;
        const delta = d * c;
        h *= delta;
        if (Math.abs(delta - 1) < 1e-15)
            break;
    }
    return Math.max(0, Math.min(1, factor * h));
}
export function ols(y: number[], x: number[][], lags = 0): Result {
    const n = y.length, p = x[0].length;
    same(y, x);
    if (n <= p)
        fail('INSUFFICIENT_DATA');
    integer(lags, 0, n - 1);
    const cols = tr(x), scales = cols.map(c => Math.sqrt(dot(c, c)));
    if (scales.some(s => s === 0))
        fail('SINGULAR_DESIGN');
    const q: number[][] = [], r = Array.from({ length: p }, () => Array(p).fill(0) as number[]);
    for (let j = 0; j < p; j++) {
        let v = cols[j].map(z => z / scales[j]);
        for (let pass = 0; pass < 2; pass++)
            for (let i = 0; i < j; i++) {
                const proj = dot(q[i], v);
                r[i][j] += proj;
                v = v.map((z, t) => z - proj * q[i][t]);
            }
        r[j][j] = Math.sqrt(dot(v, v));
        if (r[j][j] < 1e-10)
            fail('SINGULAR_DESIGN');
        q.push(v.map(z => z / r[j][j]));
    }
    const solve = (v: number[]): number[] => { const b = Array(p).fill(0) as number[]; for (let i = p - 1; i >= 0; i--) {
        let s = 0;
        for (let j = i + 1; j < p; j++)
            s += r[i][j] * b[j];
        b[i] = (v[i] - s) / r[i][i];
    } return b; };
    const beta = solve(q.map(c => dot(c, y))).map((b, i) => b / scales[i]), fitted = x.map(row => dot(row, beta)), residuals = y.map((v, i) => v - fitted[i]);
    const invr = tr(Array.from({ length: p }, (_, j) => solve(Array.from({ length: p }, (_, i) => Number(i === j)))));
    const bread = mm(invr, tr(invr)).map((row, i) => row.map((v, j) => v / scales[i] / scales[j]));
    const scores = x.map((row, t) => row.map(v => v * residuals[t])), meat = mm(tr(scores), scores);
    for (let lag = 1; lag <= lags; lag++) {
        const w = 1 - lag / (lags + 1);
        for (let t = lag; t < n; t++)
            for (let i = 0; i < p; i++)
                for (let j = 0; j < p; j++)
                    meat[i][j] += w * (scores[t][i] * scores[t - lag][j] + scores[t - lag][i] * scores[t][j]);
    }
    const cov = mm(mm(bread, meat), bread), se = cov.map((row, i) => Math.sqrt(Math.max(0, row[i]))), sse = dot(residuals, residuals), ym = mean(y), sst = sum(y.map(v => (v - ym) ** 2));
    return { coefficients: beta, standard_errors: se, fitted, residuals, r_squared: sst === 0 ? null : 1 - sse / sst, n, df_residual: n - p, hac_lags: lags, residual_sum_squares: sse, qr_min_diagonal: Math.min(...r.map((row, i) => row[i])) };
}
function construct(d: Data, op: string): Result {
    if (op === 'composite') {
        required(d, ['features', 'weights', 'directions']);
        const f = mat(d.features, 3), w = vec(d.weights), directions = vec(d.directions);
        same(w, directions, f[0]);
        if (Math.min(...w) < 0 || Math.abs(sum(w) - 1) > 1e-10 || directions.some(v => Math.abs(v) !== 1))
            fail('INVALID_PARAMETER');
        const z = tr(tr(f).map(standard)), components = z.map(row => row.map((v, j) => v * w[j] * directions[j])), out = components.map(sum);
        return { ids: ids(d, f.length), scores: out, components, standardized: z, primary: out[0] };
    }
    required(d, ['scores']);
    const x = vec(d.scores, 2), n = x.length, names = ids(d, n);
    if (op === 'quantile') {
        const count = integer(d.buckets ?? 5, 2, n), order = x.map((_, i) => i).sort((a, b) => x[a] - x[b] || (names[a] < names[b] ? -1 : names[a] > names[b] ? 1 : 0)), buckets = Array(n).fill(0) as number[];
        order.forEach((i, j) => buckets[i] = 1 + Math.floor(j * count / n));
        const counts = Array.from({ length: count }, (_, j) => buckets.filter(b => b === j + 1).length), weights = buckets.map(b => 1 / counts[b - 1]);
        return { ids: names, order: order.map(i => names[i]), buckets, counts, weights, primary: counts[count - 1] };
    }
    if (op === 'sector') {
        required(d, ['sectors']);
        const sectors = d.sectors;
        if (!Array.isArray(sectors))
            fail('INVALID_SHAPE');
        same(x, sectors);
        if (sectors.some((v: unknown) => typeof v !== 'string' || !v))
            fail('INVALID_SECTOR');
        const group: Record<string, number> = Object.create(null);
        for (const g of [...new Set(sectors as string[])].sort())
            group[g] = mean(x.filter((_, i) => sectors[i] === g));
        const out = x.map((v, i) => v - group[sectors[i]]), sums: Record<string, number> = Object.create(null);
        for (const g of Object.keys(group))
            sums[g] = sum(out.filter((_, i) => sectors[i] === g));
        return { ids: names, scores: out, group_means: group, group_sums: sums, primary: Math.max(...Object.values(sums).map(Math.abs)) };
    }
    if (op === 'beta_neutral' || op === 'residual') {
        required(d, [op === 'beta_neutral' ? 'betas' : 'controls']);
        const controls = op === 'beta_neutral' ? vec(d.betas).map(v => [v]) : mat(d.controls);
        same(x, controls);
        const design = controls.map(row => [1, ...row]), fit = ols(x, design, 0), u = fit.residuals as number[], gross = sum(u.map(Math.abs));
        if (op === 'beta_neutral' && gross <= 1e-12 * Math.max(1, sum(x.map(Math.abs))))
            fail('ZERO_RESIDUAL');
        const out = op === 'beta_neutral' ? u.map(v => v / gross) : u, exposures = tr(design).map(col => dot(col, out));
        return { ids: names, scores: out, residuals: u, fitted: fit.fitted, coefficients: fit.coefficients, exposures, gross: sum(out.map(Math.abs)), primary: Math.max(...exposures.map(Math.abs)) };
    }
    const p = num(d.tail ?? 0.05);
    if (p < 0 || p >= 0.5)
        fail('INVALID_PARAMETER');
    const lo = quantile(x, p), hi = quantile(x, 1 - p), clipped = x.map(v => Math.max(lo, Math.min(hi, v))), rank = ranks(clipped), out = rank.map(v => 2 * (v - 1) / (n - 1) - 1);
    return { ids: names, lower: lo, upper: hi, clipped, ranks: rank, scores: out, primary: out[0] };
}
/** D17-F03-A05 public boundary. No mutation, implicit imputation or silent failure. */
export function compute(input: unknown): Result {
    const op = "residual";
    try {
        if (!input || typeof input !== 'object' || Array.isArray(input))
            fail('INVALID_SHAPE');
        const d = input as Data;
        if (Object.values(d).some(v => v === null))
            fail('INVALID_NUMBER');
        context(d, op);
        const result = construct(d, op);
        const check = (v: unknown): void => { if (typeof v === 'number' && !Number.isFinite(v))
            fail('NUMERICAL_FAILURE'); if (Array.isArray(v))
            v.forEach(check);
        else if (v && typeof v === 'object')
            Object.values(v).forEach(check); };
        check(result);
        return { status: 'ok', method: op, ...result };
    }
    catch (error) {
        if (error instanceof ContractError)
            return { status: 'error', method: op, code: error.message };
        throw error;
    }
}
The embedded lab now expands to its full document height, keeping the article as the only scroll surface.